Deals Taking Longer but Outlook is Strong
Occupational Market
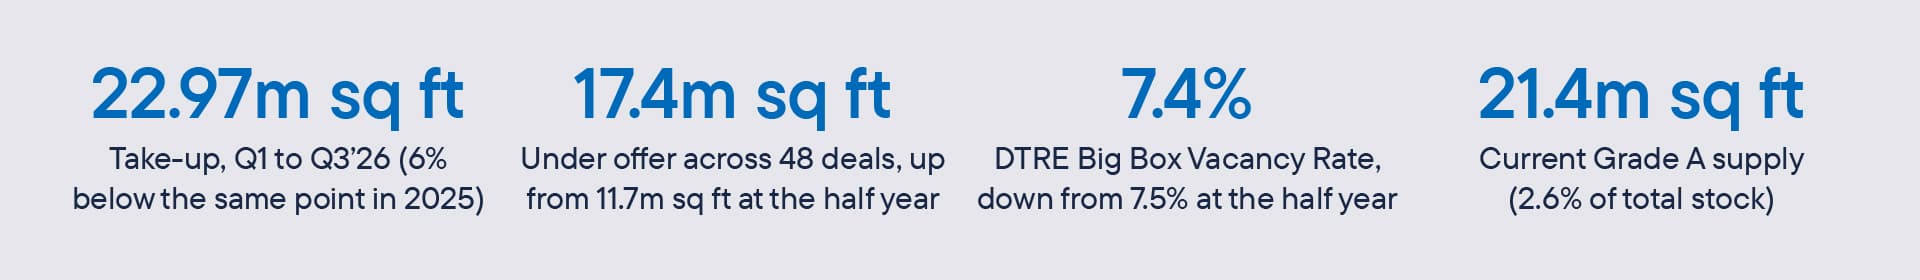
Big Box take-up reached 22.97m sq ft in the first nine months of 2026, 6% behind the same point last year but 17% ahead on a like-for-like basis once 2025’s three 1m sq ft plus deals are stripped out. With 17.4m sq ft currently under offer across 48 deals, up from 11.7m sq ft at the half year, and vacancy edging down to 7.4%, the market is slower, with deals taking longer to complete but occupiers remain no less committed.
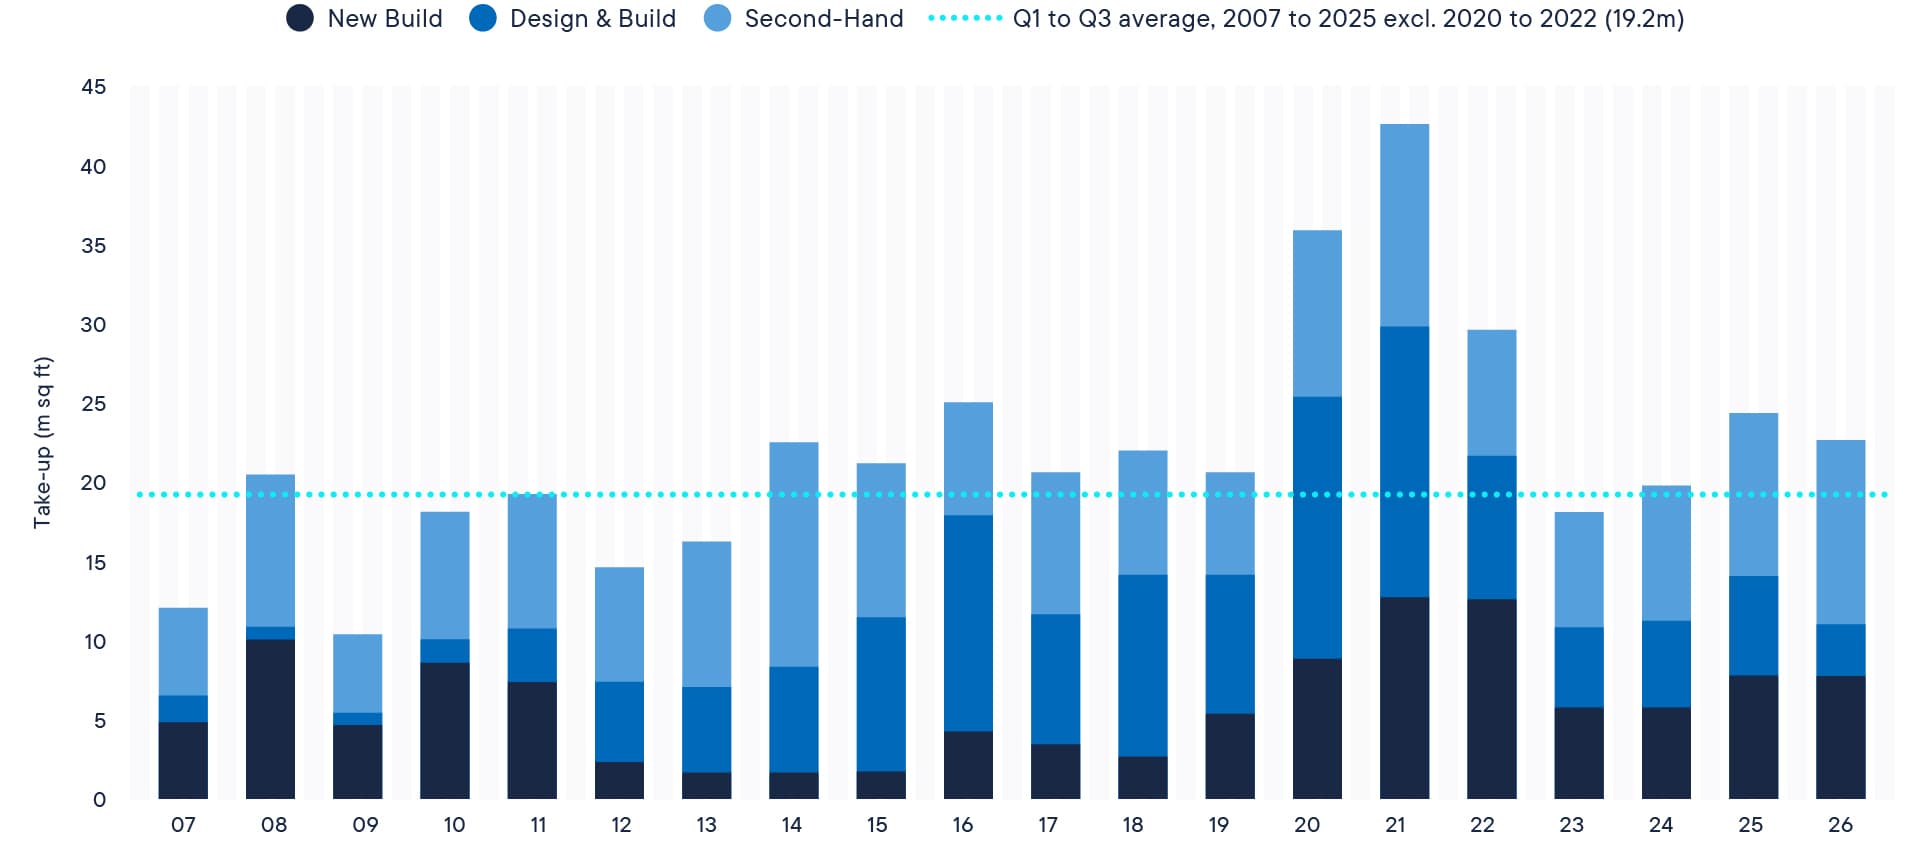
Take-up of units over 100,000 sq ft reached 22.97m sq ft in the first nine months of 2026, 6% behind the 24.5m sq ft recorded at the same point in 2025, with 7.24m sq ft landing in Q3 alone. Last year’s Q1 to Q3 figure lent heavily on three transactions over 1m sq ft totalling 4.9m sq ft, and 2026 has yet to see a completed deal of that scale. Strip those three out and the like-for-like comparison is 22.97m sq ft against 19.6m sq ft, a 17% increase, with the average deal size up from 211,000 sq ft to 247,024 sq ft across 93 deals. Q3’s 7.24m sq ft was below Q2’s 9.4m sq ft but broadly in line with Q1, and the nine-month total annualises at c.30.6m sq ft, ahead of both the three-year (28m sq ft) and ten-year (26.3m sq ft) averages and above our 30m sq ft DTRE House View base case prediction back in January. Against a noisy macro backdrop, with the Bank on hold but leaning hawkishly, 10-year gilts at a near 19-year high and a Budget still to come, the Big Box logistics market has performed admirably, even if deals are taking longer to get over the line.
Fig 1. Big Box take-up by specification, Q1 to Q3 of each year
Source: DXTRE
The quarter’s largest transactions show the breadth of demand. Palletways committed to a 637,233 sq ft D&B at Prologis Fradley and Primark took 615,000 sq ft at Sheffield 615, a reminder that well-located older stock still has a market at the right price. Manufacturing continued its strong run, with Rolls-Royce (326,243 sq ft at Derby Commercial Park), Cummins (282,000 sq ft at Ingenium Parc, Darlington), Schneider Electric (West Midlands Interchange) and Marshall Land Systems (Merthyr Tydfil) all completing, whilst retail was represented by Superdrug at Big Swan, Northampton (323,586 sq ft) and TikTok’s letting at Rugby 251. A theme we continue to watch closely is the Chinese e-commerce supply chain. JD.com has now taken two units this year (Progress Park, Bedford and another confidential deal), Super Smart Services has taken four, whilst Cainiao, JT Express and GigaCloud have all signed for space.
The ‘under offers’ also tell an important story with now 17.4m sq ft under offer across 48 deals, up from 15.8m sq ft at the end of August, 11.7m sq ft at the half year and 8.5m sq ft at the turn of the year. Just under half of it (49%) is in standing stock, which means the balance is D&B and will take longer to convert. Amazon alone is under offer on multiple units and is joined by names including Uniqlo, FedEx, Halfords, and Sainsbury’s to name but four, whilst there are also defence requirements from KNDS and RBSL in legals.
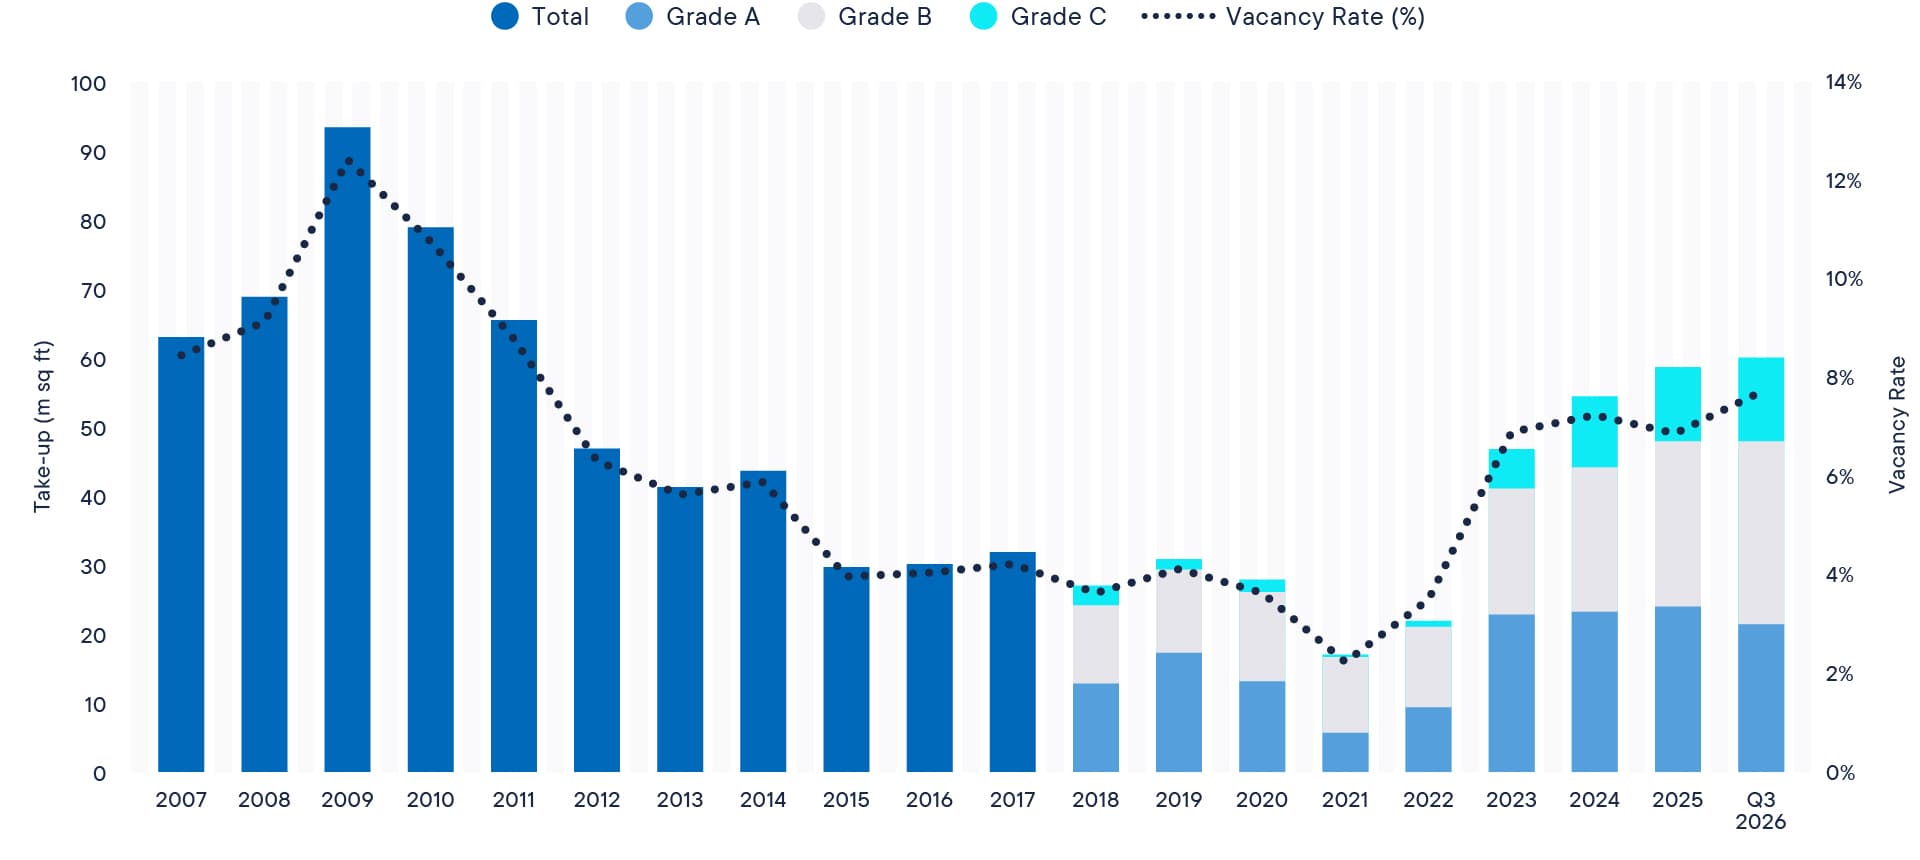
In terms of current and future supply, the DTRE Big Box Vacancy Rate edged down to 7.4% in Q3, from 7.5% at the half year, with c.59.5m sq ft available across the UK. However, the composition matters more than the headline. Grade A accounts for just 21.4m sq ft (36%) of that total, with Grade B at 26.1m sq ft and Grade C at 12.0m sq ft, meaning c.64% of what is available is ‘second-hand’ and a good proportion of that faces capex and obsolescence risk. For an occupier wanting a new Grade A unit over 300,000 sq ft, choice is already thin, and with 7.5m sq ft of speculative space across 24 units due to reach practical completion over the next 12 months (against a rolling average of c.11m sq ft) it is not about to get materially wider.
Fig 2. Big Box supply by grade and vacancy rate, 2007 to Q3 2026
Source: DXTRE
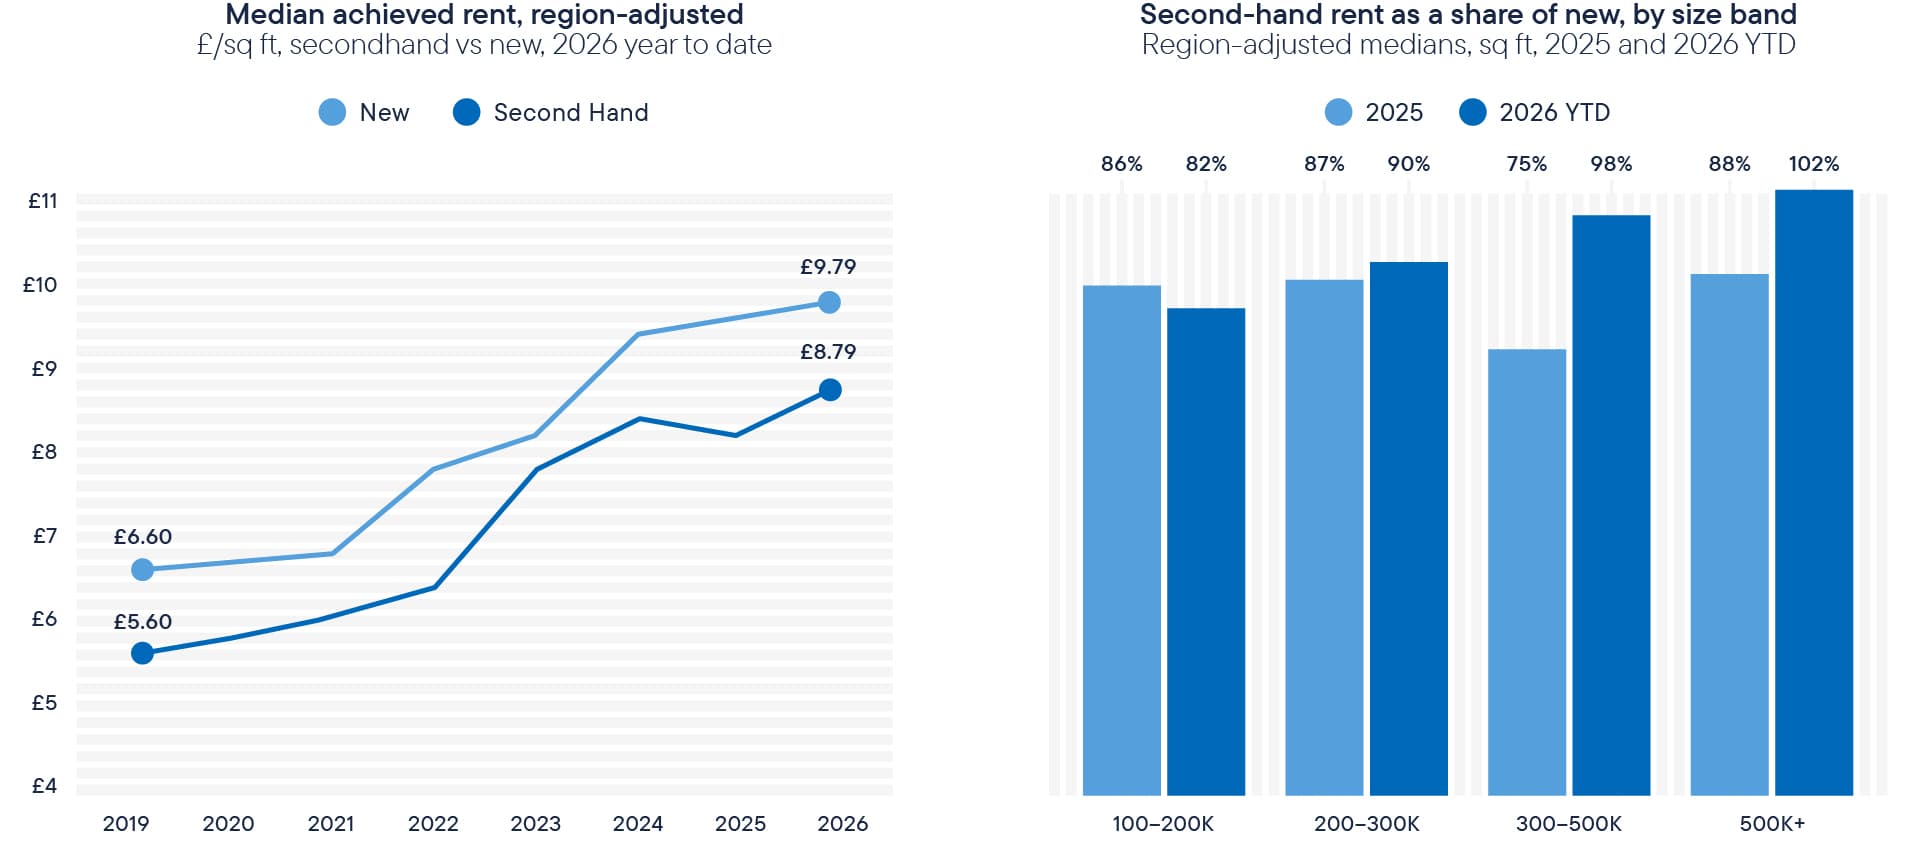
Fig 3. Achieved rents, second-hand against new build, 2026 year to date
Source: DXTRE
Rents are where the composition of supply really shows up. Second-hand rents as a share of new build now stand at 82% in the 100,000 to 200,000 sq ft band where vacancy is highest, 90% at 200,000 to 300,000 sq ft, 98% at 300,000 to 500,000 sq ft and 102% over 500,000 sq ft, the last two up from 75% and 88% a year ago.
Big Swan at £11.00 and Citadel 324 at £9.25 demonstrate that second-hand boxes are letting at or close to new-build rents, proving that second-hand units with ‘good bones’ continue to attract tenants. Overall Grade A rents keep moving up with the Grade A ‘median’ outside the South East stepping up from £8.25 in Q1 to £9.80 in Q2 and £10.13 in Q3, with ten ‘Big Box’ lettings over £10.00 this year and we expect that to continue whilst Grade A supply remains thin in the best locations.
Capital Markets
Volumes held up in Q3, with £1.64bn traded against £1.58bn a year ago, but the number of transactions has more than halved. Capital is concentrating into fewer, larger deals, but prime income is still trading, and Prologis’ recommended c.£14bn offer for SEGRO is a clear signal that global capital still sees significant upside in UK industrial and logistics.
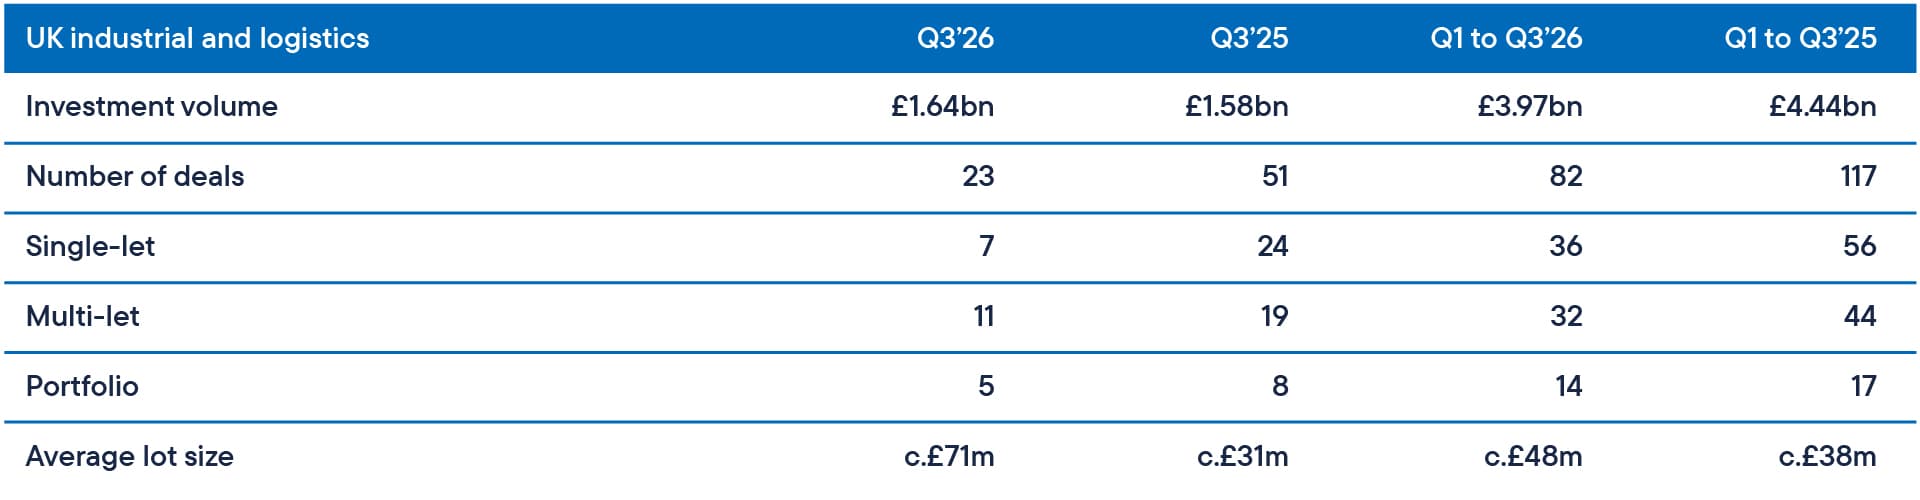
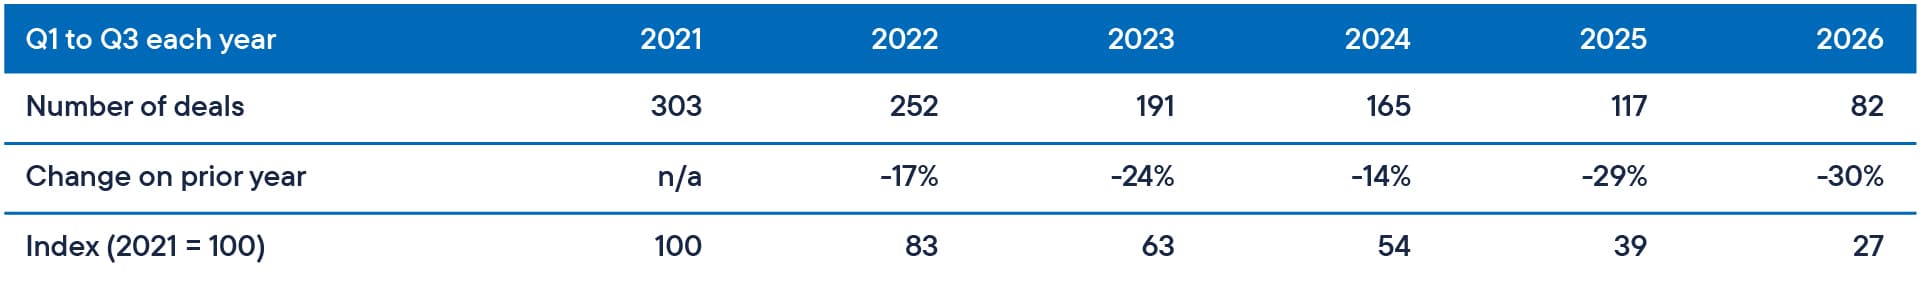
The headline number slightly flatters the quarter in which £1.64bn of UK industrial and logistics traded across just 23 deals (7 single-let, 11 multi-let and 5 portfolios), against £1.58bn across 51 deals in Q3’25. Year-to-date, £3.97bn has traded across 82 deals, 11% down on the £4.44bn and 30% down on the 117 deals recorded at the same point in 2025. There’s no doubt the market has thinned, by nearly three-quarters in five years and more than halved since 2023. However, the consequence of that is that the average lot size has more than doubled year-on-year to £71m in Q3 (from £31m), and five portfolio transactions accounted for c.£1.1bn, around two-thirds of the quarter’s volume.
Whilst the market is not short of capital looking to get in, it is short of willing vendors and of marketed stock. With 10-year gilts at 19-year highs, secondary owners have chosen to hold rather than crystallise pricing, an increasing share of what does trade is agreed ‘off-market’, and buyers are aggregating through portfolios rather than picking off single assets. Fewer, bigger and pickier is the story of 2026.
Fig 4. Investment activity, Q3’26 against prior periods
Source: DXTRE. Average lot size is volume divided by number of deals.
Fig 5. Number of UK industrial and logistics investment deals, first nine months of each year
Source: DXTRE. Completed transactions, Q1 to Q3 inclusive.
Q3 was never going to be an easy quarter for pricing given where macroeconomic conditions have begun to move. The BoE held at 3.75% on 17 September but with three members voting for a hike (a hike on 5 November now priced at a 91% chance), CPI is back up to 3.1% and heading towards 3.75%, and the 10-year gilt continues to hover around 5.4%, with the main driver being Brent oil which rode up all the way to north of $100 and has since stayed there.
Single-let Big Box evidence reflected that messy macro environment. The Sainsbury’s distribution centre at Marsh Leys, Bedford (462,746 sq ft) went to CBRE Investment Management for £67.0m and a 5.65% NIY, Invesco paid £56.9m (5.99%) for the Europa unit at Midlands Logistics Park, Corby (19.7 years), and Crossbay bought Unit 3220 Magna Park Lutterworth for £21.0m (6.67%). Long, indexed income to a strong covenant is clearing at north of 5.75%, but shorter income is being priced accordingly.
Multi-let held its ground better with standout deals at Canon Industrial Park, Wolverton at 6.19% against 6.25% quote, and Schroders paid £48.25m and a 4.01% NIY for the IPIF estates at Mammoth Drive and Radial Park.
The portfolio market did some heavy lifting with Mirastar purchasing two portfolios. Firstly, Project Leo (1.25m sq ft across four assets) from PLP for £166.6m at 5.58%, then Project Ocelot (2.71m sq ft across 8 assets) for £398m at 5.54%, EQT took Logicor’s Project Vault for £293m at 6.02%, and Farran Investments and GoldenTree acquired Paloma’s 20-asset Pintail portfolio for £193m at 6.25%. Look down the vendor column and it’s UK pension funds and balanced funds having to meet redemptions and rebalancing mandates. Who is buying? EQT, Mirastar, GoldenTree, Hines and Delancey, none of whom need to sell anything to buy. Meanwhile, the obvious standout deal was a corporate transaction as Prologis saw their c.£14bn offer for SEGRO accepted (1,031.7p per share), at a 14% premium to the June NAV of 905p and is a strong vote of confidence in UK logistics real estate.
Moving into the final three months of the year, it is usually Q4 that ‘carries the year’ but I wouldn’t hold out much hope for that this year. The contents of the Budget remain largely unknown and an increase to the Bank Rate looks probable, so expect the deal count to stay low and the average ticket to stay high, and the ‘bid/ask’ to close first where the income is longest and strongest. We first wrote this at the turn of the year and it rings just as true today. In an uncertain world, income to a strong covenant is king, and we remain of the view that prime logistics is the best risk-adjusted bet in UK commercial real estate.
DTRE Definitions
Big Box: Unit of 100,000 sq ft +
Take-up: A single-let unit upon which a new lease or occupier freehold purchase has completed (does not include lease renewals/re-gears) and is not conditional upon planning. Deals that have been agreed but remain conditional to planning remain classified as ‘under offer’.
Supply: Currently available. Newly developed units are added to the supply schedule upon reaching practical completion.